• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
CMR ASSOCIATES CPA - TAX ACCOUNTING | SPEED ACCURACY | SOLUTIONS

CMR Associates - Tax | Staffing | 401k Audits

Accuracy | Solutions | Speed

  • Services
    • 401(k) Audit Services
      • 401k Pricing Tool
    • Tax Accounting
    • Business Accounting and Fractional CFO
    • Business System Implementation
    • Remote CPA Staffing
    • Business Valuation
  • About Us
  • New Clients
    • Pricing Tool
    • Onboarding
  • Resources
    • Client Portal
    • IRS Authorization
  • Contact Us
  • Show Search
Hide Search

Business Tax Advice

Thinking about converting from a C corporation to an S corporation?

Louisiana CPA- Thinking about converting from a C corporation to an S corporation

Thinking about converting from a C corporation to an S corporation?

The right entity choice can make a difference in the tax bill you owe for your business. Although S corporations can provide substantial tax advantages over C corporations in some circumstances, there are plenty of potentially expensive tax problems that you should assess before making the decision to convert from a C corporation to an S corporation.

Here’s a quick rundown of four issues to consider:

LIFO inventories. C corporations that use last-in, first-out (LIFO) inventories must pay tax on the benefits they derived by using LIFO if they convert to S corporations. The tax can be spread over four years. This cost must be weighed against the potential tax gains from converting to S status.

Built-in gains tax. Although S corporations generally aren’t subject to tax, those that were formerly C corporations are taxed on built-in gains (such as appreciated property) that the C corporation has when the S election becomes effective, if those gains are recognized within five years after the conversion. This is generally unfavorable, although there are situations where the S election still can produce a better tax result despite the built-in gains tax.

Passive income. S corporations that were formerly C corporations are subject to a special tax. That tax kicks in if their passive investment income (including dividends, interest, rents, royalties, and stock sale gains) exceeds 25% of their gross receipts, and the S corporation has accumulated earnings and profits carried over from its C corporation years. If that tax is owed for three consecutive years, the corporation’s election to be an S corporation terminates. You can avoid the tax by distributing the accumulated earnings and profits, which would be taxable to shareholders. Or you might want to avoid the tax by limiting the amount of passive income.

Unused losses. If your C corporation has unused net operating losses, they can’t be used to offset its income as an S corporation and can’t be passed through to shareholders. If the losses can’t be carried back to an earlier C corporation year, it will be necessary to weigh the cost of giving up the losses against the tax savings expected to be generated by the switch to S status.

Additional factors

These are only some of the factors to consider when a business switches from C to S status. For example, shareholder-employees of S corporations can’t get all of the tax-free fringe benefits that are available with a C corporation. And there may be issues for shareholders who have outstanding loans from their qualified plans. These factors have to be taken into account in order to understand the implications of converting from C to S status.

Contact us. We can explain how these factors will affect your company’s situation and come up with strategies to minimize taxes.
Small businesses: Stay clear of a severe payroll tax penalty

Louisiana CPA- Small businesses Stay clear of a severe payroll tax penalty

Small businesses: Stay clear of a severe payroll tax penalty

One of the most laborious tasks for small businesses is managing payroll. But it’s critical that you not only withhold the right amount of taxes from employees’ paychecks but also that you pay them over to the federal government on time.

If you willfully fail to do so, you could personally be hit with the Trust Fund Recovery Penalty, also known as the 100% penalty. The penalty applies to the Social Security and income taxes required to be withheld by a business from its employees’ wages. Since the taxes are considered property of the government, the employer holds them in “trust” on the government’s behalf until they’re paid over.

The reason the penalty is sometimes called the “100% penalty” is because the person liable for the taxes (called the “responsible person”) can be personally penalized 100% of the taxes due. Accordingly, the amounts the IRS seeks when the penalty is applied are usually substantial, and the IRS is aggressive in enforcing it.

Responsible persons

The penalty can be imposed on any person “responsible” for the collection and payment of the taxes. This has been broadly defined to include a corporation’s officers, directors, and shareholders under a duty to collect and pay the tax, as well as a partnership’s partners or any employee of the business under such a duty. Even voluntary board members of tax-exempt organizations, who are generally exempt from responsibility, can be subject to this penalty under certain circumstances. Responsibility has even been extended in some cases to professional advisors.

According to the IRS, being a responsible person is a matter of status, duty and authority. Anyone with the power to see that the taxes are paid may be responsible. There is often more than one responsible person in a business, but each is at risk for the entire penalty. Although taxpayers held liable may sue other responsible persons for their contributions, this is an action they must take entirely on their own after they pay the penalty. It isn’t part of the IRS collection process.

The net can be broadly cast. You may not be directly involved with the withholding process in your business. But let’s say you learn of a failure to pay over withheld taxes and you have the power to have them paid. Instead, you make payments to creditors and others. You have now become a responsible person.

How the IRS defines “willfulness”

For actions to be willful, they don’t have to include an overt intent to evade taxes. Simply bowing to business pressures and paying bills or obtaining supplies instead of paying over withheld taxes due to the government is willful behavior for these purposes. And just because you delegate responsibilities to someone else doesn’t necessarily mean you’re off the hook.

In addition, the corporate veil won’t shield corporate owners from the 100% penalty. The liability protections that owners of corporations — and limited liability companies — typically have don’t apply to payroll tax debts.

If the IRS assesses the penalty, it can file a lien or take levy or seizure action against the personal assets of a responsible person.

Avoiding the penalty

You should never allow any failure to withhold taxes from employees, and no “borrowing” from withheld amounts should ever be allowed in your business — regardless of the circumstances. All funds withheld must be paid over on time.

If you aren’t already using a payroll service, consider hiring one. This can relieve you of the burden of withholding and paying the proper amounts, as well as handling the recordkeeping. Contact us for more information.

Small businesses: Get ready for your 1099-MISC reporting requirements

Louisiana CPA- Small businesses. Get ready for your 1099-MISC reporting requirements

Small businesses: Get ready for your 1099-MISC reporting requirements

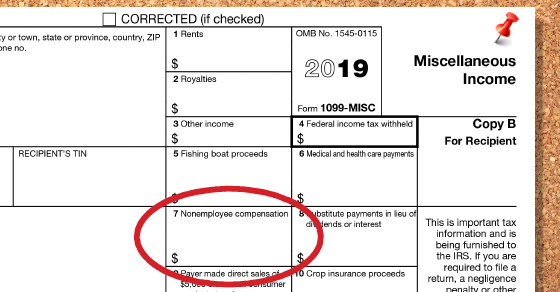
A month after the new year begins, your business may be required to comply with rules to report amounts paid to independent contractors, vendors and others. You may have to send 1099-MISC forms to those whom you pay nonemployee compensation, as well as file copies with the IRS. This task can be time consuming and there are penalties for not complying, so it’s a good idea to begin gathering information early to help ensure smooth filing.

Deadline

There are many types of 1099 forms. For example, 1099-INT is sent out to report interest income and 1099-B is used to report broker transactions and barter exchanges. Employers must provide a Form 1099-MISC for nonemployee compensation by January 31, 2020, to each noncorporate service provider who was paid at least $600 for services during 2019. (1099-MISC forms generally don’t have to be provided to corporate service providers, although there are exceptions.)

A copy of each Form 1099-MISC with payments listed in box 7 must also be filed with the IRS by January 31. “Copy A” is filed with the IRS and “Copy B” is sent to each recipient.

There are no longer any extensions for filing Form 1099-MISC late and there are penalties for late filers. The returns will be considered timely filed if postmarked on or before the due date.

A few years ago, the deadlines for some of these forms were later. But the earlier January 31 deadline for 1099-MISC was put in place to give the IRS more time to spot errors on tax returns. In addition, it makes it easier for the IRS to verify the legitimacy of returns and properly issue refunds to taxpayers who are eligible to receive them.

Gathering information

Hopefully, you’ve collected W-9 forms from independent contractors to whom you paid $600 or more this year. The information on W-9s can be used to help compile the information you need to send 1099-MISC forms to recipients and file them with the IRS. Here’s a link to the Form W-9 if you need to request contractors and vendors to fill it out: https://bit.ly/2NQvJ5O.

Form changes coming next year

In addition to payments to independent contractors and vendors, 1099-MISC forms are used to report other types of payments. As described above, Form 1099-MISC is filed to report nonemployment compensation (NEC) in box 7. There may be separate deadlines that report compensation in other boxes on the form. In other words, you may have to file some 1099-MISC forms earlier than others. But in 2020, the IRS will be requiring “Form 1099-NEC” to end confusion and complications for taxpayers. This new form will be used to report 2020 nonemployee compensation by February 1, 2021.

Help with compliance

But for nonemployee compensation for 2019, your business will still use Form 1099-MISC. If you have questions about your reporting requirements, contact us.

The tax implications if your business engages in environmental cleanup

Louisiana CPA- The tax implications if your business engages in environmental cleanup

The tax implications if your business engages in environmental cleanup

If your company faces the need to “remediate” or clean up environmental contamination, the money you spend can be deductible on your tax return as ordinary and necessary business expenses. Of course, you want to claim the maximum immediate income tax benefits possible for the expenses you incur.

These expenses may include the actual cleanup costs, as well as expenses for environmental studies, surveys and investigations, fees for consulting and environmental engineering, legal and professional fees, environmental “audit” and monitoring costs, and other expenses.

Current deductions vs. capitalized costs

Unfortunately, every type of environmental cleanup expense cannot be currently deducted. Some cleanup costs must be capitalized. But, generally, cleanup costs are currently deductible to the extent they cover:

  • “Incidental repairs” (for example, encapsulating exposed asbestos insulation); or
  • Cleaning up contamination that your business caused on your own property (for example, removing soil contaminated by dumping wastes from your own manufacturing processes, and replacing it with clean soil) — if you acquired that property in an uncontaminated state.

On the other hand, remediation costs generally have to be capitalized if the remediation:

  • Adds significantly to the value of the cleaned-up property,
  • Prolongs the useful life of the property,
  • Adapts the property to a new or different use,
  • Makes up for depreciation, amortization or depletion that’s been claimed for tax purposes, or
  • Creates a separate capital asset that’s useful beyond the current tax year.

However, parts of these types of remediation costs may qualify for a current deduction. It depends on the facts and circumstances of your situation. For example, in one case, the IRS required a taxpayer to capitalize the costs of surveying for contamination various sites that proved to be contaminated, but allowed a current deduction for the costs of surveying the sites that proved to be uncontaminated.

Maximize the tax breaks

In addition to federal tax deductions, there may be state or local tax incentives involved in cleaning up contaminated property. The tax treatment for the expenses can be complex. If you have environmental cleanup expenses, we can help plan your efforts to maximize the deductions available.

2 valuable year-end tax-saving tools for your business

Louisiana CPA- 2 valuable year-end tax-saving tools for your business

2 valuable year-end tax-saving tools for your business

At this time of year, many business owners ask if there’s anything they can do to save tax for the year. Under current tax law, there are two valuable depreciation-related tax breaks that may help your business reduce its 2019 tax liability. To benefit from these deductions, you must buy eligible machinery, equipment, furniture or other assets and place them into service by the end of the tax year. In other words, you can claim a full deduction for 2019 even if you acquire assets and place them in service during the last days of the year.

The Section 179 deduction

Under Section 179, you can deduct (or expense) up to 100% of the cost of qualifying assets in Year 1 instead of depreciating the cost over a number of years. For tax years beginning in 2019, the expensing limit is $1,020,000. The deduction begins to phase out on a dollar-for-dollar basis for 2019 when total asset acquisitions for the year exceed $2,550,000.

Sec. 179 expensing is generally available for most depreciable property (other than buildings) and off-the-shelf computer software. It’s also available for:

  • Qualified improvement property (generally, any interior improvement to a building’s interior, but not for the internal structural framework, for enlarging a building, or for elevators or escalators),
  • Roofs, and
  • HVAC, fire protection, alarm, and security systems.

The Sec. 179 deduction amount and the ceiling limit are significantly higher than they were a few years ago. In 2017, for example, the deduction limit was $510,000, and it began to phase out when total asset acquisitions for the tax year exceeded $2.03 million.

The generous dollar ceiling that applies this year means that many small and medium sized businesses that make purchases will be able to currently deduct most, if not all, of their outlays for machinery, equipment and other assets. What’s more, the fact that the deduction isn’t prorated for the time that the asset is in service during the year makes it a valuable tool for year-end tax planning.

Bonus depreciation

Businesses can claim a 100% bonus first year depreciation deduction for machinery and equipment bought new or used (with some exceptions) if purchased and placed in service this year. The 100% deduction is also permitted without any proration based on the length of time that an asset is in service during the tax year.

Business vehicles

It’s important to note that Sec. 179 expensing and bonus depreciation may also be used for business vehicles. So buying one or more vehicles before December 31 may reduce your 2019 tax liability. But, depending on the type of vehicle, additional limits may apply.

Businesses should consider buying assets now that qualify for the liberalized depreciation deductions. Please contact us if you have questions about depreciation or other tax breaks.

  • « Go to Previous Page
  • Page 1
  • Page 2
  • Page 3
  • Page 4
  • Interim pages omitted …
  • Page 21
  • Go to Next Page »

Primary Sidebar

Tax. Accounting. Solutions.

Need a good accountant? We can help. Serving clients globally, we embrace distributed work environments. Book a call to learn more.

About CMR Associates

Covington CPA and Tax Accountants Team

Tax Accounting, 401k Audits, and Business Consulting: We provide tax accounting, 401k Audit, business accounting, Outsourced CFO, back-office CPA staffing, business system implementation, payroll support, business valuation, consulting, and …

Publication by CMR Associates

Charles Renwick CPA

All of the latest publications from the directors and staff at CMR …

TAX NEWS AND ADVICE

  • Business Tax Advice
  • Individual Tax Advice
  • Outsourced Accounting
  • Personal Finance
  • Remote Work

Terms and Conditions
Outsourced Accountant CPA
All the Presidents’ Taxes
401k Audit Services CPA

Get solutions today with CMR Assocaites. Learn More

CMR Associates - Tax |  Staffing | 401k Audits

© 2026 · Sitemap

  • Services
  • About Us
  • New Clients
  • Resources
  • Contact Us